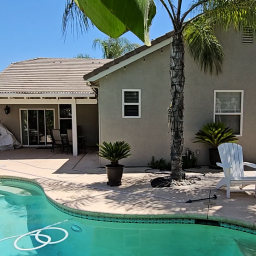
A hard to insure property is any home or residential dwelling that might have been declined for coverage by standard insurers.
In this post I will share some quick faq’s to help you determine if your property qualifies for this program.
Do you accept risks with a lapse in coverage? Yes, our firm represents several companies that will accept a residential property that has been without insurance.
Do you accept seasonal or short-term homes/condos? We will only write seasonal, short-term, Airbnb, VRBO rentals for existing clientele. As a new client to our agency we will only accept owner or tenant occupied properties that have a 6-month minimum lease in place.
Do you write mobile homes or manufactured homes? Yes, TCS Insurance brokers represents the top mobile home insurers in California.
Do you offer multiple policy discounts? Yes, multi-policy discounts are available for most of the insurance products we represent and it can be across several carrier lines. As long as our agency holds those polices as broker on record.
Do you accept properties with prior losses or with a history of claims? Yes, our carrier partners accept homes with prior losses.
Do you allow pools on the property? Yes, above ground, in-ground swimming pools, hot tubs, spas and jacuzzis are acceptable as long as the property is fenced. Diving boards and water slides may be accepted but pool liability can be excluded.
Do you write properties under a Trust, LLC or Corporation? Yes, but only under the following circumstances:
- Trusts are eligible as the named insured for both Homeowners and Landlord policies
- An LLC is an acceptable named insured for a landlord policy, but not acceptable as the named insured for a homeowner’s policy
- For an LLC to be acceptable the listed owner, managing member, or partners must be limited to an individual, or an individual and spouse/domestic partner and their family members; the LLC cannot participate in any other commercial business than the rental of the investment property
- Any other corporation is ineligible
What type of roofs are acceptable? All types of roofs except wood shingle.
What is the oldest year home that you can insure? We can offer coverage for homes built 1900 and newer.
Do you insure ADUs? Yes, under a landlord policy a frame built ADU is acceptable as long as it’s at a minimum of 500 square feet.
Are bars on windows acceptable in the hard to insure property program? No. Bars on the windows are not acceptable, not even quick release.
Can dogs listed in the unacceptable dog breed list be accepted? Yes, but animal liability coverage will be excluded.
For homes built prior to 1960, do you require documented updates? All homes will be required to have a roof in good condition, circuit breakers for electrical system, central heating system, and plumbing made of copper, PEX or PVC. All homes built prior to 1960 will qualify for coverage under the Functional Replacement Cost valuation only.
What if my home is older than 1900, has galvanized steel pipes, is located in a high risk area, or does not qualify based on the above mentioned FAQs? If your property does not qualify for any specialty or surplus program, your only option might be the CA FAIR Plan ( CPF, the insurer of last resorts). If you are a new client to our agency, we will direct you back to your current insurance provider for help. If you are an existing Auto, Home or Business client of TCS Insurance Brokers, we can assist you with obtaining coverage in the CFP. Along with presenting a difference in conditions option (companion policy).
At TCS Insurance Brokers, we’re here to help California homeowners protect their assets in a challenging insurance landscape. Whether it’s shopping for better coverage, advising on risk management, or connecting you with reliable service providers, our team has you covered.
If you would like us to review your current policy or help you compare options to ensure you do not have these critical gaps, please reach out. —proactive steps today can save you stress and money tomorrow.
Blog post written by Domingo Ramos, CA Lic. 0F53636, National Producer Number 9071660
Need help you with Home Insurance?
Simply Complete a formal quote request on our get a quote page and I or one of my amazing licensed brokers will reach out with a solution that meets your needs.